UK Gambling Sector Braces for Tax Overhaul and Revenue Squeeze as Regulations Tighten
Written by Mara Walter · Mar 20, 2026
UK Gambling Sector Braces for Tax Overhaul and Revenue Squeeze as Regulations Tighten
The Latest Revenue Dip Hits Online Betting Hard
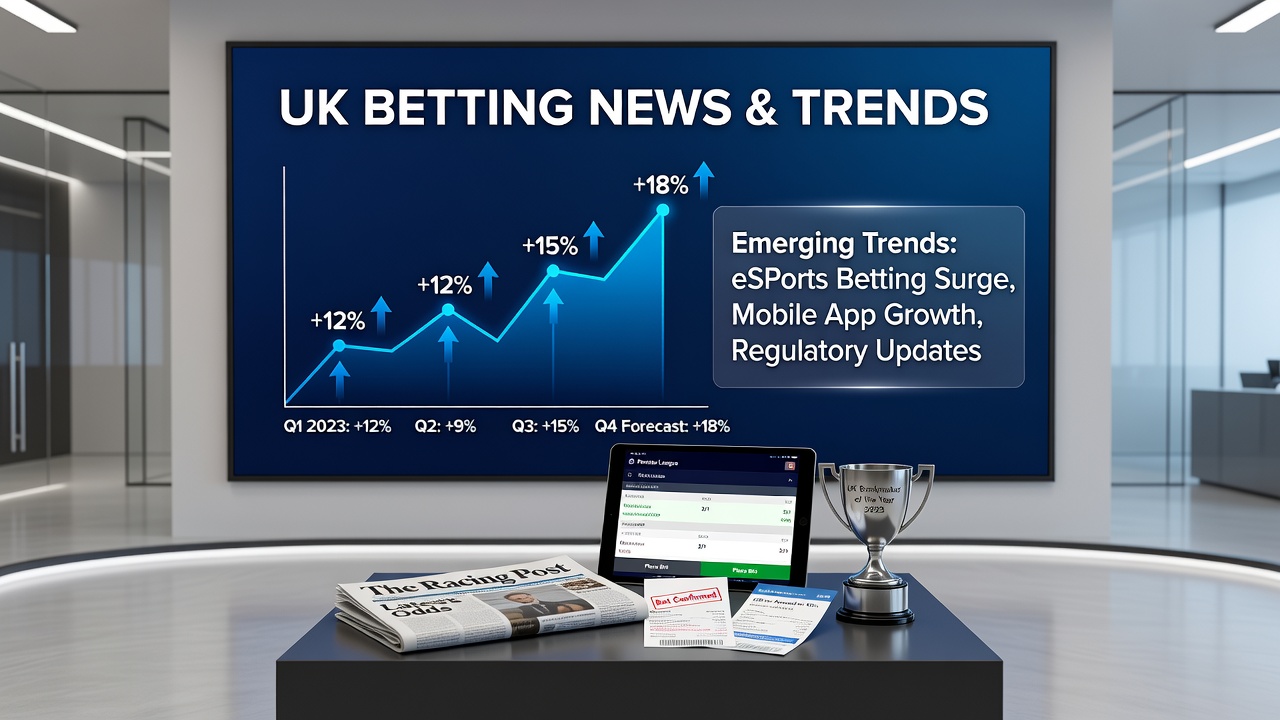
Figures from the final quarter of 2025 reveal a notable decline in the UK's online gross gambling yield (GGY), dropping compared to the same period the previous year, primarily because real-event betting underperformed while other segments held steadier. Data indicates this slump caught operators off guard, especially since land-based gambling showed resilience in contrast. Experts tracking the sector note how real-event betting, which includes sports like football and horse racing, drives a significant portion of online revenues, so when it weakens—due to factors like fewer high-profile events or shifting punter habits—the impact ripples across the board.
But here's the thing: this isn't happening in isolation; stricter regulations from the UK Gambling Commission layer on extra pressure, forcing companies to rethink strategies even as tax bills loom larger. Observers point out that the combination creates a perfect storm, where yields fall just as costs climb, squeezing margins in ways that demand quick adaptations.
Tax Hikes Set to Reshape the Landscape from April 2026
Starting April 2026, the government plans a major overhaul of gambling duties, hiking the remote gaming duty from its current 21% rate all the way to 40%, a move that targets online operators head-on since remote gaming covers slots, casino games, and similar digital offerings. At the same time, bingo duty faces elimination, which could ease burdens for that niche but doesn't offset the broader hit to online platforms; meanwhile, a new statutory levy kicks in, projected to raise £100 million each year specifically for research, prevention, and treatment of gambling harm.
Those who've studied fiscal impacts in gaming sectors know these changes aren't subtle—they're seismic, potentially altering how firms price odds, manage bonuses, and even target markets, all while compliance costs rise under the Gambling Commission's watchful eye. And with March 2026 marking the ramp-up to these reforms, operators already scramble to model scenarios, adjusting budgets months ahead because the clock ticks fast in this regulated space.
Regulatory Tightening Adds Layers of Compliance
The UK Gambling Commission, alongside government bodies, drives these reforms with a focus on player protection, introducing measures that demand more robust age verification, affordability checks, and advertising curbs, all of which ramp up operational expenses for license holders. Data shows how past tweaks—like stake limits on online slots—already trimmed yields; now, with taxes doubling on remote duties, the sector faces compounded effects that could push some players toward unregulated offshore sites, although regulators aim to close those gaps too.
What's interesting is the shift underway: land-based venues, less affected by remote duty hikes, might see a relative uptick as punters wary of online taxes flock back to high streets, yet online remains the growth engine, handling over 80% of GGY in recent years according to industry trackers. Operators respond by leaning harder into digital innovations—think AI-driven personalization or crypto integrations—but profitability hangs in the balance, especially with the statutory levy pulling £100 million annually straight from revenues.
Operators Voice Concerns Over Profit Margins and Market Shifts
Industry leaders highlight profitability as the core worry, with models suggesting the 40% remote duty could erode up to 20% of net profits for pure online plays, prompting consolidations or exits among smaller firms; take one mid-tier operator who recently warned stakeholders that without offsets—like bingo duty scraps failing to balance the scales—closures loom on the horizon. Yet larger players, those with diversified portfolios spanning retail and digital, position themselves better, using scale to absorb hits while investing in compliance tech.
Turns out, the market tilts further digital despite the taxes, as younger punters prefer apps over arcades; figures reveal online GGY still dwarfs land-based by multiples, even post-2025 dip, so operators pivot toward slots and virtual sports—segments less tied to real events that faltered last quarter. And here's where it gets interesting: the statutory levy, while earmarked for harm reduction, sparks debate on efficiency, with experts questioning if £100 million truly addresses root issues or just pads budgets, although data from pilot programs shows promise in treatment uptake.
Real-Event Betting's Weakness Exposed in Q4 2025 Data
Diving deeper into that Q4 2025 slump, real-event betting—encompassing everything from Premier League matches to Cheltenham races—saw yields contract sharply, possibly linked to a quieter sporting calendar or economic headwinds curbing disposable spends; non-real segments like poker or e-sports held firmer, underscoring how event dependency creates volatility that taxes exacerbate. People in the know observe that punters chased value amid tighter wallets, opting for lower-stake accumulators over big singles, which diluted overall GGY.
So, as April 2026 nears, firms experiment with hybrid models—blending real-event thrills with virtual alternatives—to stabilize flows, all under the Commission's mandate for fair play. Observers note one case where a major bookie rolled out enhanced live-streaming early, clawing back some ground lost in the dip, proving adaptability pays off when regulations and taxes converge.
Broad Implications for Players, Jobs, and the Economy
Beyond operators, these shifts touch players who might encounter higher odds or fewer promos as costs pass through, although harm-focused levies aim to foster safer environments with better tools for self-exclusion and spend tracking. Jobs in the sector, numbering tens of thousands across tech, compliance, and retail, face scrutiny too, with online-heavy firms trimming headcounts to offset duties; land-based spots, buoyed by bingo changes, could add roles in customer-facing areas.
Economically, the Treasury eyes that £100 million levy as a win for public health funding, yet sector contributions to GDP—around £15 billion yearly—risk contraction if yields keep sliding. But the reality is, historical precedents like the 2019 triennial review show industries adapt, often emerging leaner and more tech-savvy, so while Q4 2025 stings, the full picture unfolds through 2026.
Experts who've tracked similar overhauls in places like Australia or Sweden point to consolidation as the norm: fewer but stronger players dominate, channeling levies into visible reforms that build trust. It's noteworthy that March 2026 brings interim reporting requirements, giving a sneak peek at how firms weather the storm before April's full force hits.
Conclusion
The UK gambling industry's path forward hinges on navigating this trifecta of declining Q4 2025 online GGY, a remote duty leap to 40%, and a £100 million statutory levy, all under heightened Gambling Commission oversight that prioritizes harm reduction over unchecked growth. Data underscores the real-event betting lull as a key drag, yet opportunities emerge in digital diversification and compliance leadership. As operators adjust—modeling profits, innovating products, and lobbying for tweaks—the sector demonstrates resilience, much like it has through past regulatory waves; what's significant is how these changes, rolling out from March into April 2026, redefine an industry long synonymous with high stakes and calculated risks.