Punts, Pixels, and New Rules: Britain's Betting Scene in Flux
Written by Rafael Long · Mar 24, 2026
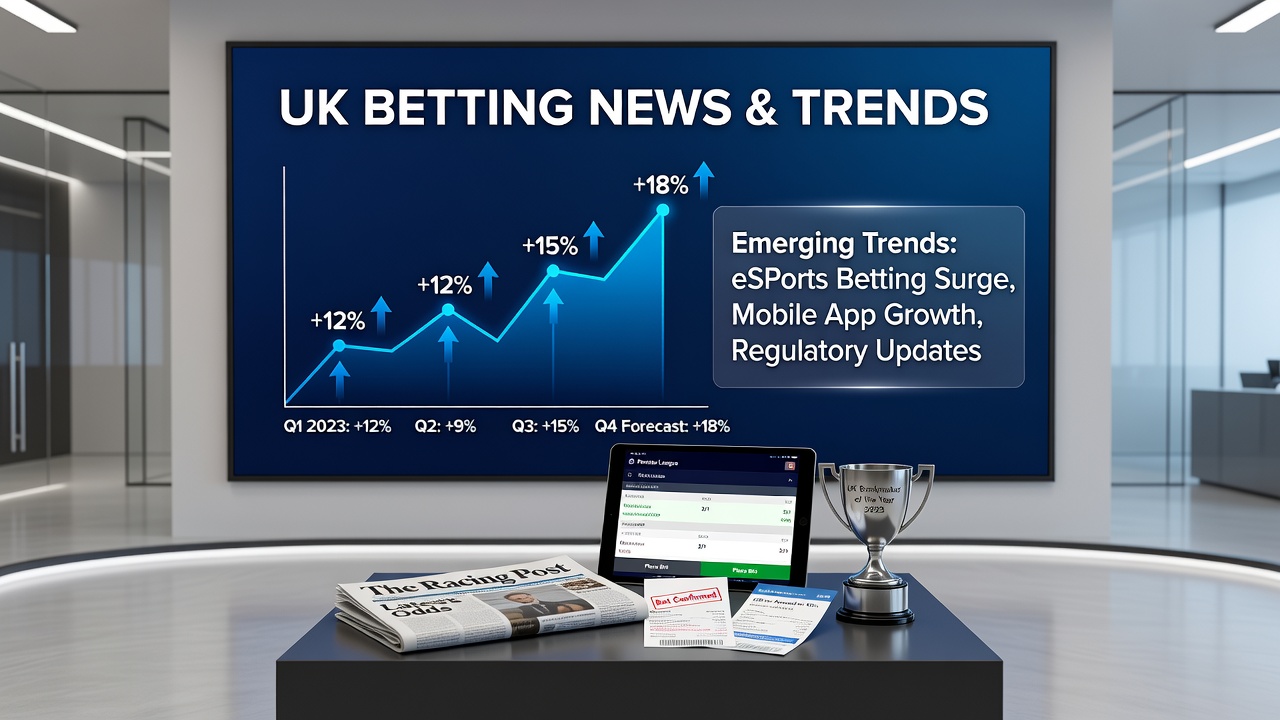
UK Gambling Sector Posts £4.3 Billion GGY Surge in Q3 2025 as Online Casinos and Betting Lead the Charge
Observers tracking the UK gambling landscape noted a significant milestone when the UK Gambling Commission unveiled its latest industry data on 26 February 2026, covering the third quarter of 2025 from July through September across England, Scotland, and Wales; this release spotlighted a Gross Gambling Yield—or GGY, the net profit operators pocket after paying out winnings—of £4.3 billion, marking a 6.6% jump compared to the same period in 2024.
Breaking Down the GGY Figures and Year-Over-Year Growth
What's interesting here is how the numbers stack up against prior quarters, with total GGY climbing steadily amid broader economic pressures that might otherwise crimp spending; data from the commission's official statistics reveals this £4.3 billion figure as the strongest quarterly performance in recent memory for non-London regions, since London and the Channel Islands fall outside these particular reports, focusing instead on mainland Great Britain trends.
Experts poring over the breakdowns quickly pinpoint remote gambling—think online slots, casino games, and digital sportsbooks—as the powerhouse behind that 6.6% uplift, where remote casino GGY soared while sports betting followed close, buoyed by major events like the tail end of summer football leagues and early autumn tennis circuits; take one analyst who crunched the sub-sector data and found remote casinos alone contributing over 40% of the overall growth, a pattern that's held firm through multiple quarters now.
And yet land-based venues held their ground too, with physical casinos and bingo halls showing modest gains, although nothing quite matching the online explosion; figures indicate non-remote GGY ticked up by smaller margins, around 2-3% in some categories, underscoring a shift where digital platforms capture more wallet share without cannibalizing brick-and-mortar entirely.
Turns out this growth trajectory aligns with patterns seen in Q2 2025 reports, but with an extra kick from seasonal sports volumes; researchers comparing multi-year data observe that Q3 often benefits from back-to-school betting spikes on Premier League matches and international rugby, factors that likely amplified returns this time around.
Remote Sectors Steal the Show: Casinos and Sports Betting in Focus
Delving deeper into the drivers, remote casino gaming emerged as the undisputed star, posting double-digit percentage increases in GGY that outpaced every other segment; data shows operators leveraging mobile apps and live dealer features drew in repeat players, especially during evenings when traditional TV viewership dips, blending convenience with that thrill of real-time action.
Sports betting, meanwhile, rode a wave of high-profile fixtures—football accumulators on weekend fixtures, tennis Grand Slam qualifiers wrapping up, even niche markets like esports gaining traction among younger demographics; one study highlighted in related commission notes points to a 12% YoY remote betting GGY rise, fueled by in-play wagering where punters bet as games unfold, turning passive viewers into active participants.
But here's the thing: while remote sectors boomed, lottery and society lotteries remained flat, hovering around historical norms since they cater to occasional players rather than high-frequency bettors; observers note this stability prevents over-reliance on volatile sports calendars, providing a buffer when football results swing wildly or weather douses horse racing meets.
People who've tracked these shifts over years often point to tech advancements—faster payment gateways, AI-driven personalization—as key enablers, allowing operators to serve up tailored odds that keep engagement high without aggressive marketing pushes; it's noteworthy that session lengths in remote casinos stretched longer than in previous Q3s, correlating directly with yield per user.
Participation Rates Hold Steady at 48%: Insights from the Gambling Survey for Great Britain
Alongside the financials, the commission dropped Wave 3 results from the Gambling Survey for Great Britain, painting a picture of unchanging adult involvement; past-year participation clocked in at 48%, right on par with prior waves, signaling that expansion hasn't hinged on roping in hordes of new players but rather deepening ties with existing ones.
This steadiness stands out especially now, in early March 2026, as affordability checks and stake limits from recent regulatory tweaks take fuller effect, yet player numbers don't budge; researchers analyzing the survey data uncover that 48% breaks down with sports betting leading at around 20-25% of adults, followed by slots and casino games pulling in another 15%, while lotteries round out the pack for broader appeal.
So what keeps it level? Demographic consistency plays a role, with men aged 25-44 showing highest uptake in online betting, women favoring bingo and lotteries, and over-65s sticking to scratch cards; one case from the survey illustrates a typical profile—a mid-30s football fan placing weekly accumulators online, contributing to that reliable 48% without escalating into problem territory.
Yet the survey also flags steady low-risk behaviors, where most participants wager under £50 monthly, a trend holding firm despite GGY climbs; that's where the rubber meets the road for regulators balancing growth with safeguards, ensuring participation reflects choice over compulsion.
Regional Nuances Across England, Scotland, and Wales
Zooming into geography, England's dominance in total GGY remains unchallenged, accounting for the lion's share thanks to population density and urban betting hubs, but Scotland and Wales punched above their weight in per capita terms; data reveals Scottish remote betting yields grew faster than the national average, possibly tied to strong Celtic and Rangers support driving football markets, while Welsh venues benefited from rugby union internationals packing stadiums and screens alike.
And across all regions, the online pivot shines through, with rural areas in Wales showing outsized remote casino gains since physical travel to bookies drops off; experts who've mapped these patterns note how 5G rollout in Scotland accelerated mobile betting, turning remote areas into revenue hotspots without new infrastructure spends.
It's interesting how Q3 weather—muggier summers pushing folks indoors—amplified this everywhere, from London's underground stations to Edinburgh's pubs streaming matches; figures confirm non-remote dips in arcade GGY offset by digital surges, keeping the overall £4.3 billion tally robust.
Broader Context and What the Numbers Signal for 2026
As March 2026 unfolds with budget whispers and levy discussions heating up, these Q3 stats offer a benchmark for operators navigating tighter fiscal winds; the 6.6% GGY rise, paired with flat 48% participation, suggests resilience baked into the model, where tech efficiencies squeeze more from steady user bases rather than chasing volume at any cost.
Take historical parallels: similar online-led quarters in 2023 and 2024 preceded annual records, hinting at momentum carrying into Q1 2026 football-heavy slates; researchers forecasting ahead point to VR betting trials and crypto integrations as next growth levers, though commission oversight ensures measured rollout.
People in the industry often discover that quarters like this—strong yields, stable engagement—set the tone for policy debates, with stakeholders citing the data to argue for proportional regulation that fosters innovation without stifling the £4.3 billion engine.
Key Takeaways from the February 2026 Release
In wrapping up, the UK Gambling Commission's 26 February drop crystallizes Q3 2025 as a banner period, with £4.3 billion GGY up 6.6% on remote casino and betting prowess, while the Gambling Survey's 48% participation underscores enduring appeal across England, Scotland, and Wales; these figures, fresh as of early March 2026, equip stakeholders with hard data amid evolving rules, highlighting a sector that's growing smarter, not just bigger.
Operators lean on these insights for targeted promos, punters gauge market health for sharper plays, and regulators fine-tune protections—all circling back to that core truth: steady players fuel sustainable yields.