High Stakes Shift: What's Shaking Up Britain's Betting Landscape Right Now
Written by Mia Lehmann · Apr 18, 2026
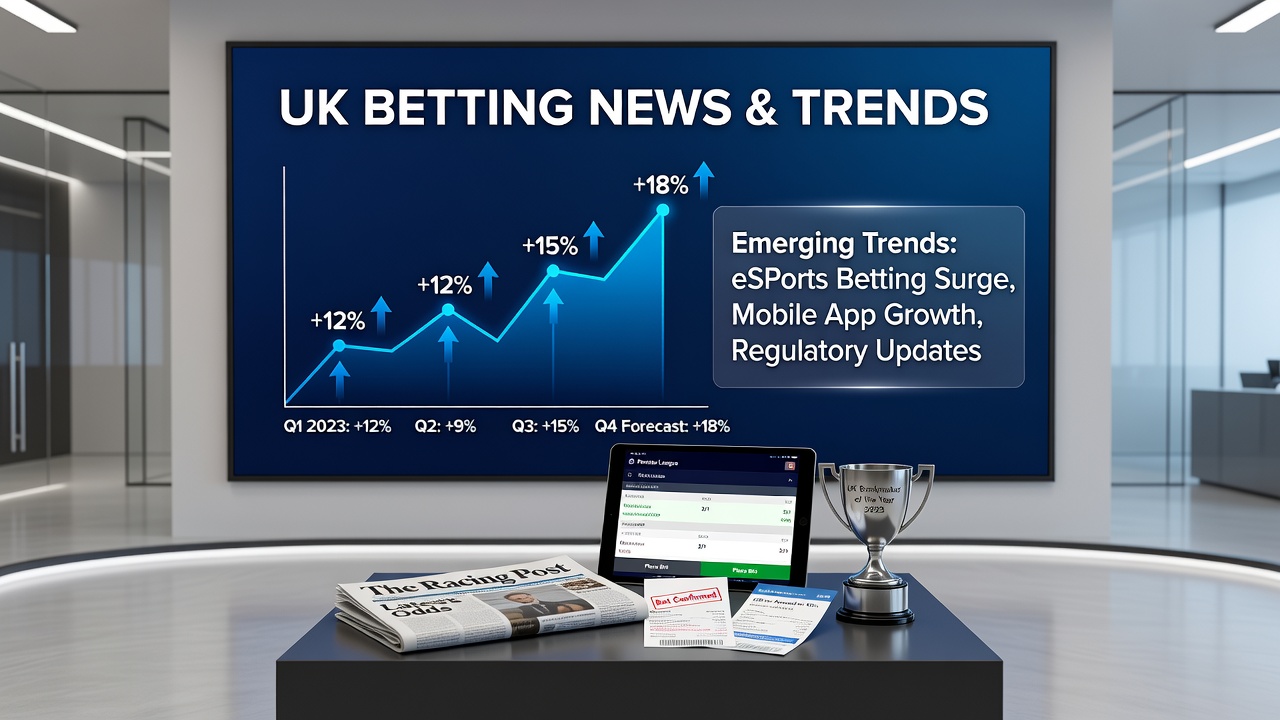
UK Gambling Commission Defends Targeted Financial Risk Assessments Amid Fierce Industry Backlash
The Spark Igniting the Debate in April 2026
Observers watched closely this April 2026 as the UK Gambling Commission stepped up to defend its proposed Financial Risk Assessments—or FRAs—against a wave of industry backlash, with Director of Major Policy Projects and Evaluation Helen Rhodes directly addressing swirling rumors that these checks would slap blanket spending caps on everyday bettors. Turns out, that's not the case at all; Rhodes made it clear during recent statements that FRAs zero in on just the top 3% of high-spending customers, using open banking data to verify whether they're truly in financial difficulty, while the vast majority of punters sail through unaffected. And here's where it gets interesting: Minister Ian Murray backed this up, pointing to pilot data showing that 97% of these assessments would run frictionlessly, meaning no heavy-handed interruptions for most.
People in the sector have been buzzing about this since the proposals surfaced, especially as they tie into broader reforms from the 2023 Gambling Act review White Paper, yet the Commission emphasized that FRAs stand alone as a targeted tool, not some sweeping overhaul designed to crimp casual wagering. Data from early pilots revealed stark patterns among those flagged customers—they're 2-4 times more likely to carry debt management plans—highlighting why regulators see value in these checks, even as operators push back hard.
Unpacking FRAs: What They Actually Target and How They Work
Those who've dug into the details note that FRAs aren't about micromanaging every bet placed across the UK; instead, operators must run these assessments on the highest-spending 3% of their customer base, pulling in open banking insights to spot genuine financial distress, which could stem from mounting debts or other red flags. Rhodes laid it out plainly when refuting claims of universal spending limits, stating outright, "This is not the case," because the system flags only those at elevated risk, leaving the other 97% to bet without added friction, as pilots confirmed.
But here's the thing: pilots tested this in real-world scenarios, and the numbers spoke volumes—affected customers showed dramatically higher rates of debt issues, 2-4 times the norm—which underscores the rationale, since unchecked high-rolling can lead to serious problems down the line. Experts observing the rollout point out that open banking, already a staple in financial services, provides a seamless data feed; operators access affordability signals without bettors lifting a finger in most instances, making 97% of checks invisible and swift, according to Murray's affirmations based on those trials.
Take one operator involved in early testing; they found the process streamlined far beyond initial fears, with automated approvals handling the bulk, while the rare manual reviews focused precisely where risks peaked, ensuring compliance without broad disruption. And while critics argued these checks morph into de facto caps—limiting stakes for high spenders—Rhodes shut that down, clarifying that FRAs verify vulnerability but don't arbitrarily halt play; they prompt protections like reality checks or temporary timeouts only if distress confirms.
Industry Pushback Meets Firm Regulatory Resolve
The Betting and Gaming Council led the charge against FRAs, voicing concerns that even targeted checks burden operators with red tape and deter big bettors, yet the Commission held ground, with Rhodes methodically dismantling misconceptions one by one. Rumors flew fast about blanket caps stifling the market, but she countered with facts: these assessments hit only the top 3%, using proven open banking tech to differentiate true risk from healthy high-stakes play, and pilots proved the frictionless path for nearly everyone else.
What's significant is how this defense unfolded publicly in April 2026, right as the Aintree Festival wrapped— an event that spotlighted unregulated betting woes, with the Betting and Gaming Council reporting over £100m wagered on black market sites during the meet, a trend signaling punters fleeing strict rules for shadowy alternatives. Regulators seized on that, arguing FRAs help keep activity onshore and protected, since high-risk players slipping into distress fuel migration to unlicensed operators lacking safeguards.
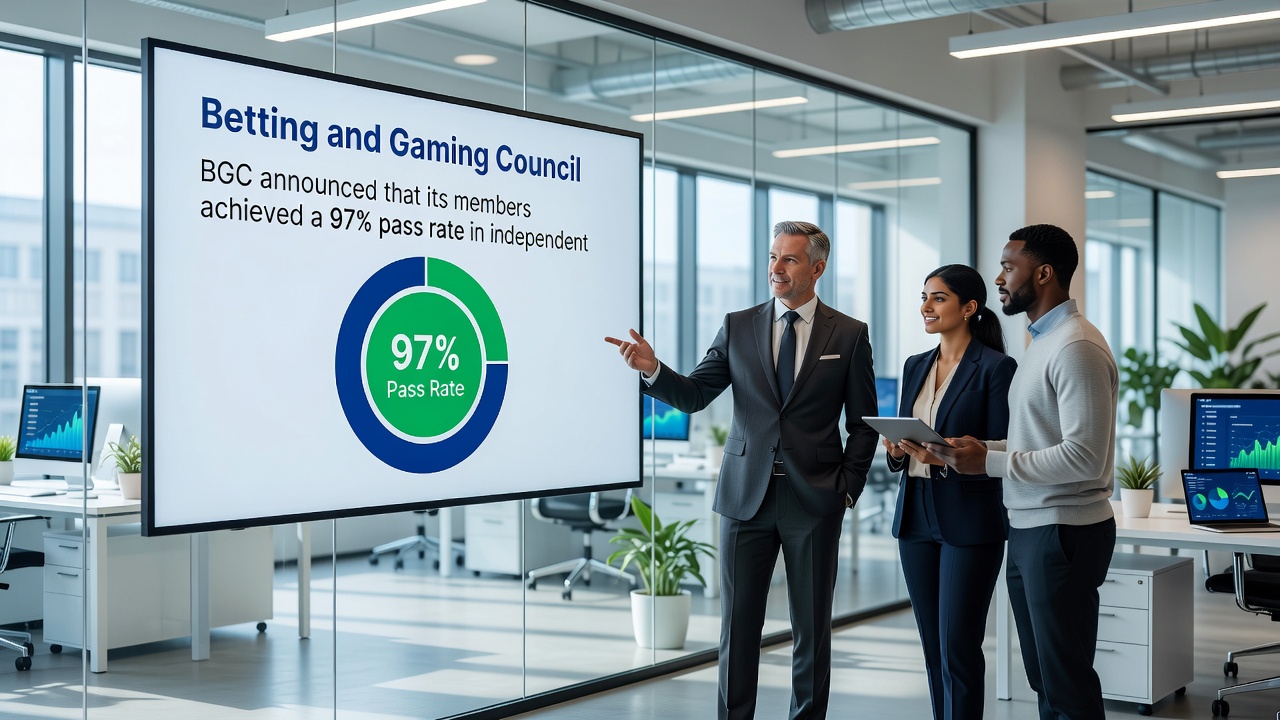
Operators countered that such checks, even if narrow, complicate compliance; they worry top customers—those driving revenue—might walk if flagged repeatedly, but Commission data from pilots suggests otherwise, with minimal drop-off and high automation rates keeping operations smooth. Murray's endorsement added political weight, as he highlighted the 97% frictionless figure, drawn straight from trial runs, positioning FRAs as a balanced fix rather than an overreach.
Pilot Data Paints a Clear Picture of Risk and Efficiency
Now, pilot results offer the hard evidence backing the Commission's stance; among the top 3% high-spenders scrutinized, debt management plans appeared 2-4 times more frequently than across the broader base, a statistic that figures from SBC News reveal in detail, showing why targeted intervention makes sense. These customers, often wagering big on events like Aintree, represent not just revenue but vulnerability hotspots, where unchecked play spirals into financial trouble.
Yet efficiency shone through too—97% of assessments zipped by frictionlessly, relying on open banking's instant data pulls, which spared bettors from endless forms or delays; only the confirmed at-risk few faced deeper dives, like self-declarations or spending pauses. Observers who've reviewed the pilots note this tiered approach mirrors banking norms, where high-value accounts trigger reviews without alienating users, and Murray stressed exactly that in his support, framing FRAs as pragmatic evolution, not revolution.
One case from the trials stands out: a cohort of high-spenders flagged early showed intervention curbed escalation, with many opting into self-exclusion voluntarily post-check, averting worse outcomes—all while the system clocked near-perfect automation for the rest. That said, the black market shadow loomed large during Aintree, where £100m poured into unregulated pools, per Betting and Gaming Council tallies; such shifts happen when bettors sense overregulation, yet regulators argue FRAs prevent that by safeguarding players without scaring off the responsible majority.
Black Market Bets Highlight Stakes Beyond the Regulations
Amid the FRA fray, the Betting and Gaming Council dropped a bombshell from the recent Aintree Festival—over £100m wagered on black market sites—a figure that underscores emerging trends where punters dodge licensed books for untaxed, unprotected action. This isn't isolated; as FRAs roll out, operators fear accelerated flight if checks feel intrusive, but the Commission points to pilots proving minimal impact on the 97% unaffected, urging focus on reeling in those offshore losses.
High-stakes events like Aintree amplify this, drawing big bets that black markets snatch when rules tighten; yet data indicates flagged customers' debt vulnerabilities make them prime targets for shady sites promising no limits, which is why FRAs aim to intervene early. Rhodes and team position this as protective, not punitive—using open banking to affirm financial health keeps players in regulated spaces, where funds stay taxed and safe, contrasting the wild west of illicit platforms.
People tracking these patterns observe that £100m at one festival alone signals billions potentially at risk yearly; FRAs, by design, target exactly those prone to such slips, with pilots validating the 2-4x debt multiplier and frictionless scale. Murray's nod reinforces the government's buy-in, tying it to white paper goals of accountability without overkill.
Navigating the Path Forward for Operators and Regulators
So as April 2026 unfolds, the clash over FRAs boils down to trust in the data—pilots affirm efficiency and necessity, countering backlash with specifics on the top 3%, open banking, and debt realities—while black market stats remind everyone of the alternatives. Operators adapt by integrating tech for seamless compliance; regulators refine based on trials, ensuring 97% frictionless holds true at scale.
Those studying the sector see this as the rubber meeting the road for post-white paper reforms, where targeted tools like FRAs balance protection and play, especially with Aintree-style events exposing unregulated pulls. Rhodes' firm "This is not the case" echoes as the line in the sand, backed by Murray and pilots alike.
Conclusion
In wrapping up the April 2026 defense of FRAs, the UK Gambling Commission clarified a targeted approach for the top 3% high-spenders, refuting cap rumors with pilot-proven frictionless checks for 97%, debt insights 2-4 times higher in that group, and warnings from £100m black market wagers at Aintree. This positions FRAs as a precise safeguard amid industry heat, keeping betting robust yet responsible as reforms advance.